

BrightWay Credit Card Mobile
4.6

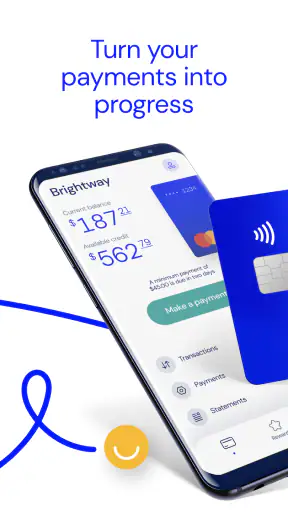
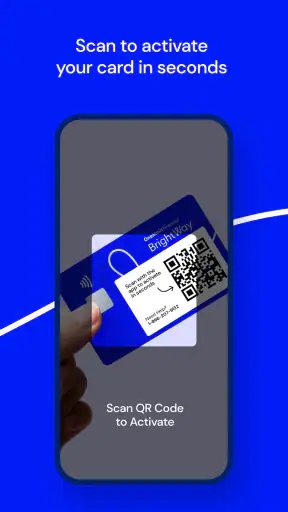
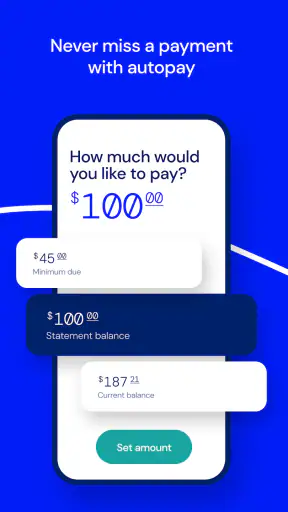
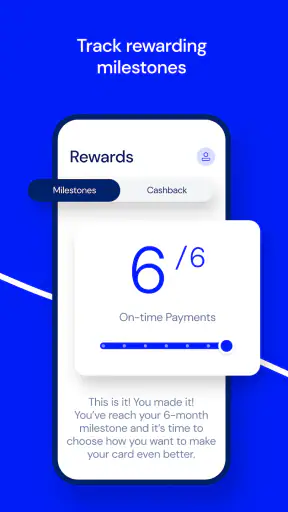
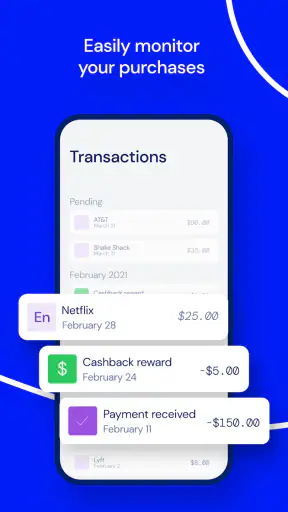
Managing a credit card from a phone sounds simple until an app makes a routine payment feel slow, confusing, or unnecessarily stressful. I spent time looking at BrightWay Credit Card Mobile as a finance app built around the BrightWay Credit Card, and my overall impression is that it is most useful when you want a focused place to check spending, handle payments, and keep an eye on rewards. It is not trying to be a complete budgeting system, and that distinction matters before you install it.
The app is free, developed by OneMain Financial, and intended for everyone from an age-rating perspective. It has attracted a 4.6 average from around 15 thousand ratings, with more than 500 thousand installs, which gives it a reassuring level of everyday visibility without making it feel like a general-purpose banking super-app. I would recommend it first to existing BrightWay cardholders who want a convenient mobile companion rather than to someone searching for a new card-management service.
How BrightWay Credit Card Mobile feels in everyday use
A focused starting point for card management
The strongest part of the experience is its narrow purpose. When I open a dedicated card app, I expect to find the information that matters for a card decision quickly: what I have spent, what needs attention, and whether a payment or reward task is waiting. BrightWay Credit Card Mobile is positioned around exactly those activities instead of asking me to navigate through unrelated checking, savings, investing, or insurance sections.
That focus can make the app feel more approachable than a traditional bank application. A large financial app may offer more tools, but it can also bury a card balance beneath several account types. Here, the BrightWay Credit Card remains the center of attention. For a user who checks a card several times a week, that reduced scope is a practical advantage rather than a missing feature.
I would still avoid treating the app as a replacement for a full household budget. A card-management screen can show the activity connected with this product, but it does not automatically become a complete picture of rent, cash spending, another card, or a separate bank account. I find it better to use BrightWay for card decisions and a dedicated budgeting tool, spreadsheet, or broader banking app for the rest of my financial life.
Speed expectations for routine checks
For a finance app, perceived speed is less about flashy transitions and more about whether I can reach the useful information without hesitation. BrightWay Credit Card Mobile benefits from having a clear job: checking spending, making payments, and reviewing rewards. Those are naturally short sessions. I would expect the app to feel most efficient when I open it with one specific question, such as whether a recent purchase has appeared or whether a payment needs attention.
That narrow workflow also changes how I judge performance. I do not need a card app to behave like a game or a social feed. I need readable screens, predictable movement between account areas, and a clear response after I submit a financial action. A simple design can feel faster than a feature-packed alternative even when both require a moment to load information from an online account.
There is an important distinction between the app opening quickly and account information being available immediately. Card balances, transactions, payments, and rewards depend on current account information, so a delay may come from the service connection rather than the phone itself. I would not repeatedly tap a payment button just because the confirmation screen takes a moment. In financial apps, patience is safer than assuming the first tap failed.
What happens during heavier use
Most people will not use this app continuously. The heavier moments are likely to come when reviewing several recent purchases, checking rewards after multiple transactions, or moving through payment-related screens while trying to confirm the right amount and date. These tasks place more importance on clarity and recovery than on raw animation speed.
My practical advice is to check the account before starting a payment workflow, especially if I have recently made a payment elsewhere or returned an item. That short pause helps me avoid acting on an old balance. I would also review the final confirmation carefully rather than navigating away as soon as I press a button. The app is valuable precisely because it handles financial actions, so the best performance habit is deliberate use.
BrightWay is less likely to satisfy someone who wants to analyze spending in depth across many categories and accounts. A dedicated budget app usually offers richer long-term charts, broader account connections, and more elaborate planning. The trade-off is that those alternatives can require more setup and may make a quick card check feel less direct. I prefer BrightWay when the question is specifically about the BrightWay card, not when I am trying to understand every part of my finances.
A realistic payment-day routine
Imagine I am about to pay a bill and want to confirm that a recent grocery purchase, a subscription renewal, and an older payment are all reflected correctly. I would open BrightWay Credit Card Mobile, inspect the current activity, compare the amount with what I expect, and then move to the payment area. After submitting the payment, I would keep the confirmation visible long enough to verify the details instead of closing the app immediately.
This scenario shows where the app can be genuinely useful. It puts spending and payment tasks in the same card-focused environment, so I do not have to search through unrelated financial products. It also shows why I would not rely on a single glance at a balance. A balance is useful, but the transaction list and payment confirmation provide the context needed to avoid mistakes.
For someone who shares household responsibilities, I would use the app as a personal verification tool rather than assume it replaces communication. If another person makes a payment or uses the card, the app can help me inspect the account, but it cannot by itself explain an unfamiliar purchase. That is a small but important limitation of any account screen: it reports activity; it does not resolve every real-world question behind it.
Reliability and recovering from interruptions
Reliability matters more here than visual polish. I want confidence that the app will let me review the account and that a completed action will be represented clearly. A finance app should encourage me to confirm what happened, particularly after an interrupted connection, an expired session, or a screen that takes longer than expected.
If a payment-related screen appears stuck, my first response would be to avoid submitting again immediately. I would check whether a confirmation appeared, reopen the relevant account area, and verify the activity before trying anything a second time. This recovery habit is useful with BrightWay because duplicate actions are more serious than a delayed screen in an entertainment app.
The app’s usefulness also depends on keeping the phone’s operating system compatible. BrightWay Credit Card Mobile currently lists version 5.10.0 and supports Android 6.0 or later. That broad minimum makes it approachable for people who keep an older Android phone, although an older device may still provide a less comfortable experience than a newer one. Compatibility is not the same as speed, and I would keep that distinction in mind when judging a financial app on aging hardware.
When the app does not behave as expected, I would separate three possibilities: a phone issue, a network issue, and an account-service issue. Restarting the app can help with a local display problem, while checking the connection can explain missing or delayed information. If the account itself does not reflect an action, I would rely on the app’s visible confirmation and official account support rather than guessing from a frozen screen.
Resource demands and older devices
Because this is a finance utility rather than a media-heavy app, I would expect its normal use to be relatively modest compared with video, gaming, or navigation applications. The important resource is not constant background activity but the moment when the app loads account information and processes a request. I would still avoid making claims about battery or memory usage without a device-specific test, since those results can vary widely between phones and Android versions.
On an older phone, the main friction may be less about the app’s category and more about general device conditions: limited free storage, an outdated system, a crowded network, or slow switching between apps. The listed Android requirement means some older hardware can install it, but installation alone does not guarantee a smooth experience. If my phone struggles with other modern financial apps, I would not assume this one will remove every limitation.
The app is a better fit for a user who wants one clear card task at a time than for someone who expects a large dashboard with extensive customization. Fewer moving parts can make a finance tool easier to understand, especially for a family member who finds full banking applications overwhelming. On the other hand, users who need desktop-style reporting, complex budgeting, or several financial institutions in one view may find the focused approach too narrow.
Rewards are useful when treated as a secondary check
Rewards are part of the app’s purpose, but I would not let them dominate my decision-making. A reward balance can be pleasant to monitor, yet it should not encourage spending simply to see a larger figure. I would use the rewards area as a confirmation and planning aid after reviewing the underlying card activity.
One helpful workflow is to check rewards alongside recent transactions rather than in isolation. If the balance changes, looking at the activity gives me a better chance of understanding why. If it does not change when I expect it to, I would avoid assuming the app is broken; timing and account rules can affect how financial information appears. The app provides a convenient place to look, but responsible interpretation still belongs to the user.
Where it beats ordinary alternatives
Compared with checking a card through a general bank app, BrightWay Credit Card Mobile may feel more direct because it is built around a single card relationship. There is less temptation to wander through unrelated account tools, and a user who only wants to inspect spending or payments may appreciate that simplicity.
Compared with a budgeting app, it has a different strength. A budget tool is usually better for combining multiple accounts, setting broader spending plans, and looking for patterns over time. BrightWay is more appropriate when I want the card’s own information and actions in one place. I would not choose between them as if they performed the same job; using both can make sense if I want detailed planning without giving up quick card access.
Compared with using a mobile browser, a dedicated app can feel more convenient for repeated checks because it is designed as a direct entry point. The browser may be preferable on a shared or temporary device, or for someone who does not want another app installed. For regular BrightWay card use, though, the mobile app’s focused identity is the more natural option.
Who should install it, and who should skip it
I think BrightWay Credit Card Mobile is a sensible choice for an existing BrightWay cardholder who checks purchases from a phone, prefers a focused interface, and wants payment and rewards information close at hand. It can also suit someone who finds all-in-one banking apps distracting and wants a smaller, more specific financial tool.
I would skip it if I do not have a BrightWay Credit Card or if my main goal is complete financial planning across several institutions. I would also look elsewhere if I need advanced reports, detailed category analysis, or a single dashboard for a complicated household budget. Those are not flaws in a focused card app; they are signs that I need a different kind of tool.
Privacy-conscious users should also think about context before installing any finance app. A personal phone with a lock screen and current system software is a more sensible environment than a shared device. I would not install a card-management app on a phone that other people regularly borrow unless I am comfortable with the account access and device controls involved.
My performance verdict
BrightWay Credit Card Mobile makes the most convincing case through focus rather than breadth. Its job is to help BrightWay cardholders manage spending, payments, and rewards from a mobile device, and that narrow purpose can make routine checks feel more manageable than using a large banking application. The app is free, carries an Everyone age rating, and comes from OneMain Financial, while its current version and Android compatibility make it accessible to a wide range of users.
My main caution is to judge it as a card companion, not as a complete money-management system. Its perceived speed will depend on the phone, connection, and account service as well as the app itself. During payment activity, careful confirmation matters more than rushing through screens. On older hardware, it may install successfully while still feeling less responsive than it would on a newer device.
After weighing those points, I would recommend it to the right audience: BrightWay cardholders who want a straightforward mobile place to review activity, make payments, and monitor rewards. The best reason to use BrightWay Credit Card Mobile is not that it replaces every financial tool, but that it keeps one important card workflow focused and easy to revisit. If that matches the way I manage credit, it is a practical app to keep installed; if I need broad budgeting and financial analysis, I would pair it with or choose a more comprehensive alternative.
4.6
6.82K Reviews
Pros
- Quick access to balances
- payments
- and recent card transactions
- Payment reminders can help reduce the risk of missed due dates
- In-app controls make it easier to monitor card activity
- Digital statements reduce reliance on mailed paperwork
- Useful account tools are available without visiting a branch
Cons
- Some features may require an active BrightWay card account
- Approval and account services are limited to eligible users
- App usefulness depends on a stable internet connection
- Transaction updates may not appear immediately after purchases
- Support options may be less convenient outside business hours


